
Self - Credit Builder & Cards
- Rating
- 4.7
- Downloads
- 1.00M
- Content Rating
- Everyone
Self - Credit Builder & Cards - Screenshots
Pros
- Helps establish payment history with regular
- manageable credit-building payments.
- Reports eligible account activity to major credit bureaus.
- Offers secured card options without requiring a traditional credit score.
- Mobile app makes payments
- balances
- and account tracking convenient.
- May provide access to educational tools for improving credit habits.
Cons
- Membership or service fees may reduce the value for some users.
- Credit-building results are not guaranteed and take time to appear.
- Some features and limits may depend on eligibility or location.
- Late or missed payments can negatively affect your credit history.
- Funds or credit limits may be restricted compared with standard cards.
Self - Credit Builder & Cards - Description
- App Name
- Self - Credit Builder & Cards
- Package Name
- com.selflender.thor
- Developer
- Self Financial, Inc.
- Category
- Finance
- Last Updated
- Mar 30, 2018
- Version
- 10.0.0
When I look at a finance app, I care less about flashy dashboards and more about whether it helps with a specific money problem without creating another one. Self - Credit Builder & Cards is aimed at people who want to start or strengthen their credit history, and in my experience that makes it most interesting as a structured household tool rather than a general banking replacement. It is free to install, rated for Everyone, and developed by Self Financial, Inc.
The basic idea is easy to understand: you use the app to work toward building credit and toward a credit card, without a credit check at the starting point. That does not make credit automatic or risk-free, but it does make the app approachable for someone who has limited credit experience or wants a more deliberate route than immediately applying for conventional cards.
I would recommend looking at it as a focused credit-building service. It is not the app I would choose for tracking every household bill, replacing a shared checking account, or giving another person unrestricted access to my finances. Its value comes from keeping the credit-building goal visible and manageable.
How Self fits into a shared household routine
A realistic use case is a household where one person is trying to establish credit while another person helps with planning. For example, a young adult might use the account personally, while a parent or partner helps review the monthly budget outside the app. Self can support the first person’s credit goal, but it should not be treated as a family wallet where everyone casually moves money or makes decisions from the same login.
That distinction matters. Credit-building is personal, even when the household is sharing expenses. If one person is responsible for the account, that person needs to understand the payment schedule, the amount being committed, and the consequences of missing an obligation. A supportive household can discuss those points together, but the account owner should remain the person making informed decisions.
I found this separation useful because it prevents a common mistake: confusing shared budgeting with shared credit responsibility. A family may split rent, groceries, or utilities, yet those arrangements do not automatically make everyone equally responsible for an individual credit product. I would keep household contributions in a separate budget and use Self only after deciding exactly who owns the obligation.
For a shared device, I would be especially careful. A phone left unlocked on a kitchen counter is not a good place for a finance account. Even when several people trust one another, financial information deserves its own boundary. I would use the app on the account holder’s device, avoid passing the phone around during sign-in, and make sure everyone knows that viewing an account is not the same as being authorized to manage it.
The most important household rule is simple: shared planning should not become shared credentials. That rule is more valuable here than any convenience gained by letting several people use one profile.
What setup should look like before anyone commits
The first step should be a conversation about purpose. Is the goal to begin a credit history, improve an existing one, or work toward access to a card? Those are related aims, but they are not identical. I would not open the app merely because someone in the household suggested it. The person whose credit is involved should be able to explain what they are trying to accomplish and what payment responsibility they are accepting.
The no-credit-check starting point can remove one source of hesitation, especially for someone worried about applying for traditional credit. Still, I would not interpret that as “nothing can go wrong.” Any product connected to credit requires attention to its terms, payment timing, and account status. Before proceeding, I would read each screen carefully rather than tapping through setup just to see what happens.
I would also decide in advance where the money for scheduled obligations will come from. A practical arrangement might be a dedicated personal account with a small cushion, rather than relying on unpredictable household leftovers. If a partner or parent is contributing, write down the amount, the date, and what happens if that contribution is late. Informal promises are easy to forget when several bills arrive together.
Another useful boundary is separating education from pressure. A parent can explain why credit history matters, but should not rush a young adult into opening an account simply to meet a family target. Likewise, a partner should not treat access to the app as proof of trust. Financial trust is built through clear agreements and reliable behavior, not by sharing passwords.
Because the app is free to install, the download itself does not need to be a major financial decision. The meaningful decision comes later, when the user accepts an arrangement and takes on payment responsibilities. I would spend more time understanding that commitment than judging the app by its installation cost.
Coordinating payments without turning Self into a family bank
Self works best when the household creates a simple routine around it. I would choose one day each month to review the account, confirm that the planned funds are available, and check for any message or action that needs attention. This is not about staring at the app every day; it is about removing last-minute surprises.
A shared calendar can help, but I would keep sensitive account details out of a general family calendar. A neutral reminder such as “review credit-building payment” is enough. The account holder can then open the app privately and verify the actual information. This approach gives the household a coordination point without exposing financial details to every person who can see the calendar.
If someone else is helping with payments, I would use a clear handoff process. The account owner should confirm the amount and date, the helper should transfer or provide the agreed funds, and the owner should verify completion. A short message such as “the money is ready” is not the same as confirmation that the required payment was processed. That small difference can prevent a stressful misunderstanding.
I would also avoid making a household contribution depend on a single payday when possible. If the account owner’s income changes, the credit-building plan should be reviewed before the next obligation becomes urgent. The app may make the goal feel organized, but it cannot compensate for a budget that is already stretched beyond its limit.
One non-obvious advantage of using a focused app is that it can keep the credit objective from disappearing inside a large banking dashboard. A general finance app may show spending, subscriptions, savings, and bills all at once. Self is more narrowly oriented, which can be helpful for a beginner who needs one visible project. The trade-off is that you may still need another tool for the rest of the household’s money management.
That trade-off is important for couples. If you want joint transaction history, shared bill categorization, and a complete picture of household cash flow, a conventional banking or budgeting service may be better as the main coordination tool. Self can sit alongside that system, but I would not make it the household’s only financial app.
Age, trust, and the difference between help and control
The Everyone content rating makes the app broadly approachable from a content perspective, but age suitability is not the same as financial readiness. In my view, a teenager or young adult may understand the interface while still needing help with the consequences of missed payments, insufficient funds, or taking on an obligation they cannot maintain. A parent should explain those risks in plain language before offering assistance.
I would also avoid using the app as a test of independence. Someone who needs guidance is not necessarily irresponsible, and someone who appears confident may still misunderstand credit. A better approach is to ask the account holder to describe the plan themselves: what the account is for, where the payment money comes from, when it will be reviewed, and what they will do if income changes.
Trust has a practical side here. If a parent helps fund the arrangement, both people should agree on what information will be discussed and how often. The parent may need confirmation that the household contribution was used as intended, but that does not require permanent access to every account detail. A partner may want reassurance that bills are covered, but reassurance should come from an agreed routine rather than unplanned phone inspections.
I would skip this app for anyone who is looking for instant spending power, emergency cash, or a way to avoid learning basic credit habits. The product’s purpose is gradual progress, not a shortcut around budgeting. It is also not a good fit for a household that cannot agree on who owns the account and who is responsible for the money connected to it.
On the other hand, it can be a reasonable option for a person who feels intimidated by traditional credit applications and wants a more guided starting point. The lack of a credit check at the beginning may feel less threatening, while the focused purpose can make the next steps easier to discuss with a trusted family member.
What I would check during regular use
After setup, I would pay attention to three things: whether the account’s schedule fits the user’s real income pattern, whether the household contribution arrives early enough, and whether the user understands every new option presented in the app. Finance apps often make additional products look like natural next steps. I would treat each one as a separate decision instead of assuming that progress requires accepting everything offered.
The path toward a credit card deserves particular care. A card can be useful, but it changes the user’s relationship with spending. I would first establish a rule for repayment, such as using it only for a planned purchase and never treating the available amount as extra income. If the household cannot comfortably explain how the balance would be handled, I would postpone that step.
I would also keep personal records outside the app. Saving confirmation details, noting agreed household contributions, and maintaining a basic budget can make it easier to resolve confusion later. This is especially useful when one person manages the account and another person supplies funds. The records do not need to be complicated; a private note with dates and amounts is enough to create accountability.
Another practical tip is to review the app after an income change, not only after a missed payment. A new job, reduced hours, a move, or a large household expense can make an old plan unsuitable. Adjusting early is usually less stressful than waiting until the account becomes urgent. The app can be part of that review, but the decision should begin with the household budget.
In terms of platform reach, the app has been available since March 30, 2018, and the current version is 10.0.0. It supports devices running Android 7.0 or later. Those details matter if a household is reusing an older phone, because compatibility should be checked before assigning that device to the account holder.
How it compares with ordinary credit and budgeting alternatives
Compared with applying directly for a standard credit card, Self may feel less intimidating for someone who is concerned about a credit check or has little credit history. A conventional card can offer more immediate flexibility and may fit someone who already has strong credit habits, but it also makes it easier to spend before learning how repayment affects the budget.
Compared with a secured card, Self offers a different kind of starting experience. A secured card commonly asks the user to think about a deposit and ongoing card spending, while this app’s appeal is its structured credit-building route and its orientation toward working toward a card. Someone who wants a traditional card they can use immediately may prefer the secured-card route, provided they understand its terms.
Compared with a credit-monitoring app, Self is more action-oriented. Monitoring can help someone observe changes and learn what affects a credit profile, but observation alone does not create a plan. Self is more relevant when the user wants a specific program rather than another score screen. A monitoring service may still be useful alongside it for broader awareness.
Compared with a budgeting app, Self is much narrower. A budgeting app is better for assigning household income, tracking groceries, splitting bills, and seeing whether a family can afford a new commitment. Self is better treated as one focused part of that plan. Trying to make it perform the job of a complete household budget would leave important information elsewhere.
That narrowness is both the strength and the limitation I noticed most. Beginners may appreciate having fewer competing screens and a clear credit objective. Experienced users may find the experience too specialized if they want detailed cash-flow analysis, investment tools, or broad account aggregation. Choosing it depends on whether the credit-building task is the main problem you need to solve.
Who should use it, and who should choose another route
I think Self is worth considering for an adult with limited credit history who wants a guided route and is prepared to make consistent payments. It can also suit a household that wants to support one person’s credit goal while keeping account ownership personal. The app’s free price and approachable starting premise make it easier to investigate without paying simply to download it.
I would be more cautious if the user’s income is irregular, the household relies on last-minute transfers, or several people expect to control the same account. In those situations, the problem is not necessarily the app; the arrangement itself needs more stability. A budgeting conversation and emergency cushion should come first.
I would also choose a different option for someone whose priority is a shared family account, detailed spending reports, or immediate access to a usable card. A mainstream bank, budgeting service, secured card, or credit-monitoring tool may fit those needs better, depending on the person’s credit profile and financial habits. Self should be selected for its focused purpose, not because one app is expected to solve every money problem.
The app has earned a 4.7 average from over one hundred thousand ratings, with more than one million installs and tens of thousands of written reviews. That level of adoption suggests it is not an obscure experiment, but popularity should not replace reading the terms or checking whether the routine fits your household. A highly used finance app can still be wrong for a particular budget.
My household verdict is positive but carefully limited. I would recommend Self - Credit Builder & Cards to the person who owns the credit goal, understands the payment commitment, and wants a focused way to work toward credit and a card without beginning with a credit check. I would not recommend making it a shared-device free-for-all or using it as a substitute for household budgeting.
Used with clear boundaries, private account access, and a realistic funding plan, it can give a beginner a concrete financial project to manage. The best result comes from treating the app as a tool for building habits, not as a promise of instant improvement. That mindset makes it much easier to decide whether Self belongs in your household’s financial routine.
FAQ
What is Self - Credit Builder & Cards, and how does it work?
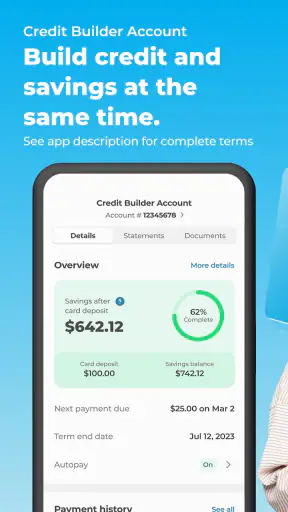
Self is a financial app designed to help users build or establish credit through a Credit Builder Account. Instead of receiving the borrowed money immediately, you generally make scheduled payments into a secured account over a selected term. Self may report payment activity to major credit bureaus, and once the account is completed, the accumulated funds are typically returned to you, minus applicable fees and interest.
Does Self - Credit Builder & Cards require a credit check?
One of Self’s main attractions is that applying for a Credit Builder Account may not require a traditional hard credit inquiry, making it accessible to people with limited or damaged credit histories. However, approval is not guaranteed, and eligibility requirements can vary. You should review the current terms carefully, including identity, income, residency, and payment-account requirements, before applying.
Can Self actually improve my credit score?
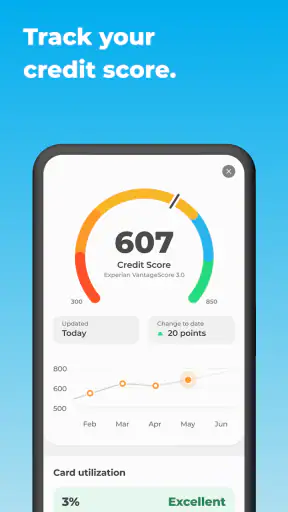
Self can help create a positive credit history when payments are made on time and the account activity is reported to the credit bureaus. Nevertheless, the app cannot guarantee a specific score increase. Your results depend on your complete credit profile, including existing debts, utilization, missed payments, account age, and the reporting policies of the bureaus. Late payments may negatively affect your credit.
What are the Self secured credit cards, and how are they different from the Credit Builder Account?
Self may offer secured credit card products connected to your Credit Builder Account. These cards generally require a refundable security deposit, which can determine your spending limit, and they are intended for everyday purchases while helping establish payment history. They are not the same as the installment account, so users should check eligibility, annual fees, interest rates, deposit rules, and reporting details before accepting a card offer.
How much does Self cost, and what should I know before signing up?
Self is not completely free. Depending on the plan and product you choose, you may pay an administrative fee, interest, card-related charges, or other costs disclosed in the agreement. You also need to budget for recurring monthly payments because missed payments can lead to fees, account problems, and possible credit damage. Compare the total repayment amount with the potential credit-building benefit before enrolling.


